Read? I am on Retirement Sum Scheme (RSS) (3)
At 65 is $1,180 for 23 yrs. End at 88
At 67 is $1,631 for 20 yrs! End at 87
Funny leh!
Delay RSS withdrawal will mean living one year shorter meh???
Walan!


Read? I am on Retirement Sum Scheme (RSS) (3)
At 65 is $1,180 for 23 yrs. End at 88
At 67 is $1,631 for 20 yrs! End at 87
Funny leh!
Delay RSS withdrawal will mean living one year shorter meh???
Walan!
Read? Time in the Market > Timing the Market??? (4)
It is very long journey with plenty of emotional rides across volatile market cycles; but when we retire with this freehold and passive dividend income! It is SWAN! Sleep Well At Night! LOL!

Read? Why Pursue Financial Freedom? (6) - Refresh!
Read? FI or FIRE? What Next? What Other FIRE Bloggers May Have Not Mentioned These
Read? You think it is so easy to retire early???
FIRE is more than just financial readiness or financial independence! We will need solid reasons or meaningful objectives to retire early. Uncle8888's block has two early retirees but they didn't called themselves Stay-at-home-dad. Women who early retired are more likely to label themselves as housewives or stay-at-home-mum. See the gender inequality or difference. LOL!
Uncle8888 just came across another case of FIRE and then back to office. It shows that early retirement is NOT that easy. It is always more than just financial means to FIRE!
Case 6 is an interesting one as he is Trainer for Early Retirement Masterclass!
Never mind! We can always FIRE and then De-FIRE after that! LOL!
Uncle8888 hasn't renewed his passport so unlikely to travel soon and no JB too! LOL!
Unlikely we can avoid future high medical costs as we grew older and older!
We can don't travel; but we cannot don't fall sick or suffer long term illness!

Read? S- REITs As Retirement Income For Cash Tight Retirees???
Probably; Uncle8888 is the odd Panda/Koala retiree in Singapore who is dis-interested in accumulating S-REITs as retirement income and still able to survive from dividend income generated from his Panda/Koala portfolio across market cycles.
Read? Three Years After Retiring From Full Time Monthly Salary As Employee (2)
Let it flows! Let it flows! Let it flows!
Don't bother with compounding growth as retiree! Enough is enough! Sustainable retirement income to ease emotional rides in volatile market.
Unrealized P/L in the portfolio is not Real; but realized cash flowing into Cash Reservoir is Real and cover future household expenses!
Every single cent flows into the Cash Reservoir and Uncle8888 has discovered this simple and practical strategy worked during COVID-19 crisis as retiree and likely to also work in future market cycles to avoid negative sequence of return risk.


Read? Leveraged Annuity Plan As Additional Source Of Mini/Nano Retirement Income???
Loan rate is rising so banks should be making more money!
18 months of loan interests payment and another 18 months to go. Monthly annuity payout after loan interests starts from 37th month.
Let see when it will hit the projected rate of 2.5% before monthly payout!

LOL! Uncle8888 has already done CPF SA to CPF RA transfer after publishing the post on buay song CPF shifting Goal posts. Now, it also makes more sense to withdraw $2K CPF OA earned interests on monthly basis starting from Jan 2023 instead of lump sum withdrawal of 11/12 months of interests earned since 2017.

Spur22 February 2022 at 23:13:00 GMT+8
Uncle8888,
U are in better position than most to make lemonade out of this lemon.
Since most of your interest comes from OA and you're starting RSS payouts soon, one solution can be to transfer your SA to RA and let it be amortized via the 25 year payouts. You'll still be getting the 4% interest plus the extra 1% and 2%.
Then every Jan, just withdraw the credited OA interest. Or you can withdraw smaller sums, every couple months or so, thus allowing more interest to be earned. Since the RSS payouts are already larger.
-------------------------------------
I was initially thinking whether can use SA shielding to preserve the SA.
i.e. shield the SA, then withdraw OA interest, then unshield the SA, do all in Jan.
But I think the $40K CPFIS-SA threshold still applies even if 55+ and already meet the retirement sum?
Cest la vie! Shit happens! 🤣
Good luck to those who have good faith in our CPF scheme and how many more shifting Goal posts waiting down the Road for you!
Read? Another New CPF Shifting Post Without Informing Affected Members!
Thursday, 22 December 2016
Read? Turning 55 - and enjoying financial freedom (5)
CW: Pls help to check how much interests I can draw out without touching my SA and OA.
CPF: Wah! You have lots of interests to draw out. It is $XX,XXX. Do you want to draw out now?
CW: :-)
CW: No. Not now. I will withdraw next year on January.
CPF: No. You can't withdraw your interests on January. Your interests credited on January will become your principal. You have no more interests to withdraw. You have to be careful as you will be withdrawing your principal in CPF SA first and then principal in CPF OA. CPF SA is 4% interests. Be careful! You better withdraw now in December. Your interests for November has been credited! Do you want to withdraw now?
CW: No. I will withdraw next year in December.
--------------------------------------------------------------------------------------
Uncle8888 clarified farther ...
Thank you for fast reply!
Quote from your reply : "As part of the Board’s ongoing efforts to ensure our administrative practices are aligned with the market practice, we have revised our practice such that only the savings in your CPF accounts can be withdrawn."
With the change of CPF administrative practices are aligned with the market practice in 2022; I can only withdraw CPF SA and CPF OA interests earned for 2022 on Jan 2023 instead of Dec 2022. Pls help to confirm my understanding is correct as below :
Estimated numbers for withdrawal from
CPF SA = $1,691 and CPF OA = $24,000 - $1,691 = $22,309. Total $24K.
It is NOT $24K from CPF SA! Right?
Thank you!
CPF''s reply ....
We refer to your enquiry via My Mailbox of 21 February 2022.
Please allow us to clarify. As explained in our replies of 17 February and 21 February 2022, if your SA balance is equal to or more than the withdrawal amount of $24,000, the full withdrawal amount will be from your SA and there will be no deduction from your OA savings.
The interest earned for 2022 will be credited to your SA and OA respectively on 1 January 2023, forming part of the principal balances and will be deducted from the principal balances upon withdrawal.
With reference to your example given, if you were to make a withdrawal after 1 Jan 2023 and your SA principal balance is sufficient for the withdrawal, the withdrawal amount from each account will be as follows: SA = $24,000 and OA = $0.
We hope the above clarifies, thank you.
Read? CPF Shifting Goal Posts. Did Merdeka Generation See It Coming???
Uncle8888 has never voluntary top up a single cent into his CPF as he kena CPF shifting goals from CPF withdrawal from 55 to 60; 60 to 62, and 62 to 65. How to trust CPF when he kena so many time!
2022; kena again! Luckily; thank to reader's alert for me to check with CPF!
It will be a SHOCK and WTF if he is not aware of new rule change and continue to withdraw $24K on Dec 2022 like past 5 year as retirement income for life! $24K outright from CPF SA instead of 11 months of earned interests! WTF!
Did Uncle8888 really miss out that communication of CPF's latest administrative practices that are aligned with the market practice in CPF News alert email to him?
----------------------------------------------------------------------------------------------------
Why change?
Hmm .. previously; we can just withdraw 11 months of CPF SA earned interests and then compounding the remaining 1 month in CPF SA at 4% rate! Now, ZERO compounding rate in CPF SA if you choose to withdraw earned interests! Hmm ...
---------------------------------------------------------------------------------------
CPF's next reply to my question
As part of the Board’s ongoing efforts to ensure our administrative practices are aligned with the market practice, we have revised our practice such that only the savings in your CPF accounts can be withdrawn.
This means that while interest is earned every month, it is only credited into your CPF accounts to form part of the account balances at the beginning of each year, and withdrawable from then on. If you make a withdrawal, savings from your Special Account (SA) will be paid first followed by your Ordinary Account (OA).
Based on your example given, as at December 2022, if your SA balance is equal to or more than the withdrawal amount of $24,000, the full amount will be withdrawn from your SA. If your SA balance is less than the withdrawal amount, your OA savings will be withdrawn to make up the balance.
As of today, your SA balance is sufficient for the full withdrawal of $24,000.
You have not replied to my questions. If you don't have answers, pls help to escalate to your experts to answer.
Every month of Dec since 2017; I have been withdrawing $24K. from CPF. Last year; the withdrawal from CPF SA and CPF OA is as followed : CPF SA : $1,545 and CPF $22,455.
Please help to confirm if there any changes when I withdraw $24K from CPF in Dec 2022
How much withdrawal from CPF SA and CPF OA? Pls help to provide the numbers as follows:
CPF SA = ? and CPF OA = ? Total withdrawal from CPF = $24K
Thank you!
------------------------------------------------------------
CPF's reply to my question:
As part of the Board’s ongoing efforts to ensure our administrative practices are aligned with the market practice, we have revised our practice such that only the savings in your CPF accounts can be withdrawn.
While CPF interest is earned every month, it is only credited into your CPF accounts to form part of the account balances at the beginning of each year, and withdrawable from then on. This is similar to market practice, where your bank interest is only withdrawable after it has been credited into your bank accounts. Hence, if you make a partial withdrawal, savings from your SA will be paid first followed by savings from your OA.
Real life lesson as retiree depending on dividends and trading profits in SGX!
Somehow; we hardly hear it loud and clear from dividend investing gurus/trainers that investing for dividends for FIRE or retirement is not that difficult. It is nothing more than a Game of Capital and War Chest against your expected household expenses during FIRE or retirement across future market cycles.
It is how you calibrate your war chest to generate sustainable cash flow from investment portfolio is critical. In short; it is about Method, Mind and Money Management!
What we can control and manage is our Mind and Money (deploy or accumulate war Chest) to build sustainable investment income across market cycles!
One picture tells the lesson learnt! Large war chest deployment into the market JUST to maintain past year investment income!
It is NOT that simple narrative or advert for FIRE movement that passive income exceeds expected expenses can FIRE across future market and economics cycles! Chun bo?


This is seldom mentioned by Singapore investment bloggers!
We can invest our CPFIS fund for long term retirement planning i.e. market timing and time in the market.
Dividends & interests withdrawal from CPFIS Refund as an extension to our CPF Life fixed income!
Read? Kep Corp : The Good, The Bad And The Ugly!
Looking forward to DBS and SCI FY 21 H2 dividends announcement. :-)

No overseas travelling!
No hopping to JB on free transport anytime on weekdays to Grab stuffs.
No RM2 shopping!
No eating out at restaurants to celebrate birthdays and festive seasons!
More home cooked meals for two and hot pot dinner is the easiest to prepare for family dinners! LOL!
Medical costs can ONLY go UP since our body after Point X can go DOWN and down!
Also signed up for Care shield Life!
Two consecutive years of minimum household expenses!
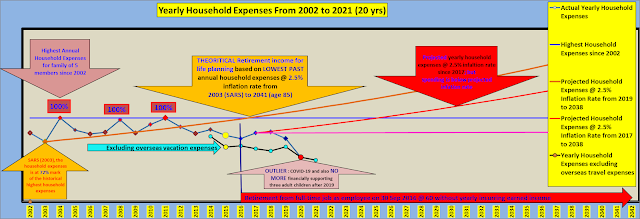

What may actually work to generate sustainable retirement income for Panda/Koala retirees in Singapore market?
The commonly recommended 3% to 4% rule based withdrawal by FAs and/or on the ground tested method based on War Chest as calibrator to generate sustainable retirement income across market and economics flowing into Cash Reservoir to minimize any down the road forced assets draw-down during market low.
Draw-down of assets during market low to support living expenses is a bad investing strategy!
5th year into retirement (2017 to 2021) - Actual outcome

Zero overseas travelling expenses in 2020 and 2021!
High medical costs as a private patient (previously on company's Class A medical benefits and down-grading is unlikely as it is better to stay with current specialists)
Health is wealth; but some health issues are not really within our control. Blame our DNA!
Read? Is CPF really the equivalent of a 60:40 fund ?
Hor! Of course; it is! LOL!
The 35% CPFIS tool is there after AFC when the MIW shifted CPF 100:100 to 65:35 and stop f... MIW for not protecting your retirement fund if you lose your money in your investment!
How to fight market volatility as retirees who are depending on their investment income?
A practical approach from unexpected lesson learnt in COVID-19 with an unplanned War Chest as one data point case study!
Read? Have you spend enough time thinking on your money management strategies? (4)
We have no control over market volatility!
We either go and fight it or slowly withdraw from it!
How to fight a War against market volatility?
Of course, we need War Chest!
How much is enough?
We have to find out ourselves! No model answer to this question!


Read? Have you spend enough time thinking on your money management stratgeies? (3)
How often have you came across investment articles or blog posts mentioning the importance aspects of money management as part of investing strategies especially during retirement phase across future crisis.
See for yourself!
Pumped in so much money into the market just to maintain!
COVID-19 has validated Uncle8888's money management strategy to sustain his replacement income from his investment portfolio during retirement phase!

We often read in blogs, forums or social media Passive income > Living expenses. Pom pi pi!. Can FIRE liao! LOL!
Lean FIRE or replacement income for retirees on dividends may NOT be sustainable over prolong market or economics crisis. We may need Plan B to level up our dividend income! Plan B. How to do that during our decumulation phase?
Lucky or unlucky; Uncle8888 learnt first-hand lesson on the ground after 3 years surviving on replacement income as Panda in local market, SGX and CPF during COVID-19. Now; he no more kpkb on rotting cash in his war chest! That is his Plan B and Plan C is to tap on his CPF RA tap for monthly cash flow:-)
Uncle8888 has to double up his investment costs during this crisis due to drastic drop in dividends from his top 3 counters to sustain his dividend income level!


Read? 1M65 CPF OA Possible Or Not???
Read? The Difference Between Smart Financial Advice and Smart Financial Advice For You (4) - Refresh!
Read? How To Become CPF Millionaire? Two Approaches Path A or B?
Read? Median household income in 2019 is $9,293
When we cannot be really motivated by Statistics then the opposite effect may happen - Demoralized??? Sigh!
Median gross monthly income from work (including CPF) in 2020 is $4.5K and after CPF is about $4K and annual income after CPF is about $48K!
Median annual income after CPF is about $48K
Mandatory annual CPF contribution is about $6K
Voluntary annual CPF Top up to Max is up to $30K for Median Income folks to become CPF millionaire!
I can! You can! LOL!
More fund for GIC to invest!
Hmm ... Sunday Times Invest Editor should be renamed to CPF Rich or Save Editor! Saving is NOT Investing! LOL!


 Posts
All Comments


